Tech_SolutionGuide_The FragmentationTaxx
by JPMorgan
The Fra gmen t a tion T ax: Wh a t M an a ging T oo M an y Banks Is A c tu all y Costing Y ou
Most technology companies don 't ha v e a banking str ategy . The y ha v e a banking hist or y , and that hist or y is quietly taxing them e v er y da y .
As technology companies scale, the y accumulate legal entities, subsidiaries, and banking accounts acr oss many countries, often because each new mark et or acquisition came with its own local bank r elationship. The r esult is fr agmentation: t oo many banks, t oo many accounts, t oo many r econciliation pr ocesses, t oo many por tals just t o understand wher e the mone y is. 13%T r easur y teams spend 13% of their time managing bank r elationships, o v erhead that should be aut omated.¹Visibility int o global oper ations, cash, and financial risk exposur esr emains out of r each when cash is scatter ed acr oss t oo many banks and t oo many por tals.The cost of fr agmentation isn ’t just inefficiency . It’ s a gr owth tax.
What this means t o the businessA gr owth tax, not just an inefficiency .
E v er y additional banking r elationship is another stack t o maintain, another integr ation t o suppor t, another place wher e capital sits idle instead of working.No single, continuous view of global cash.
Only 38% of companies achie v e continuous cash visibility via their bank, e v en though 63% achie v e some form of continuous visibility using other t ools, a gap that fr agmentation widens e v er y da y .²Idle liquidity acr oss entities.
F r agmented banking lea v es liquidity in for eign entities that can ’t be efficiently swept back t o head office, capital that should be working, not sitting idle.FX exposur e that ’ s har d t o se e and har der t o hedge.
M ultiple banking r elationships cr eate fr agmented F X e x posur e acr oss entities and curr encies, risk that’ s difficult t o aggr egate, monit or , and hedge eff ectiv ely . ⁴M anual r econciliation multiplied.
F r agmentation multiplies the integr ation points between the E RP and the bank, so e v er y r econciliation becomes a manual e x er cise, consuming tr easur y capacity that should be str ategic. ⁷T r easur y capacity consumed b y o v erhead.
T r easur y teams spend 13% of their time managing bank r elationships, o v erhead that should be aut omated, not absorbed.¹3 8%of comp anies a chieve real-time cash visibili t y vi a their bank
How we work with y ou t o help solv e itW e work with technology companies as the consolidation destination, with the br eadth of pr oduct and geogr aphic co v er age that helps r educe the need for multiple banking r elationships. W e complement, not r eplace: other pr o viders ma y handle mer chant acquiring; we handle y our tr easur y , cr oss-bor der , and systemic pa yment infr astructur e, fr om a single r elationship.Be the consolidation destination.
One team, one platform, one view , that lets a technology company gr ow without adding a new bank e v er y time it enters a new mark et.⁵A ut omate the r econciliation that fr agmentation multiplies.
Manual r econciliation can consume up t o 40% of team capacity .⁷ Spr eadsheet users spend 1.8 hours a da y on manual tasks v ersus 1.3 for those on a tr easur y platform.⁸Consolidate int o a connected financial oper ating system.
W e help bring idle capital back t o wher e it’ s most power ful, with continuous liquidity visibility acr oss e v er y curr ency , e v er y entity , e v er y mark et.²Consult for lean, under-r esour ced teams.
T ech tr easur y teams ar e small r elativ e t o the complexity the y carr y , so the y lean on aut omation and outside exper tise t o maintain contr ol.³T he goal is simple: one r elationship, one view , and the end of the fr agmentation ta x . T hat is better cash outcomes thr ough banking consolidation, power ed b y J . P . M or gan P a yments.
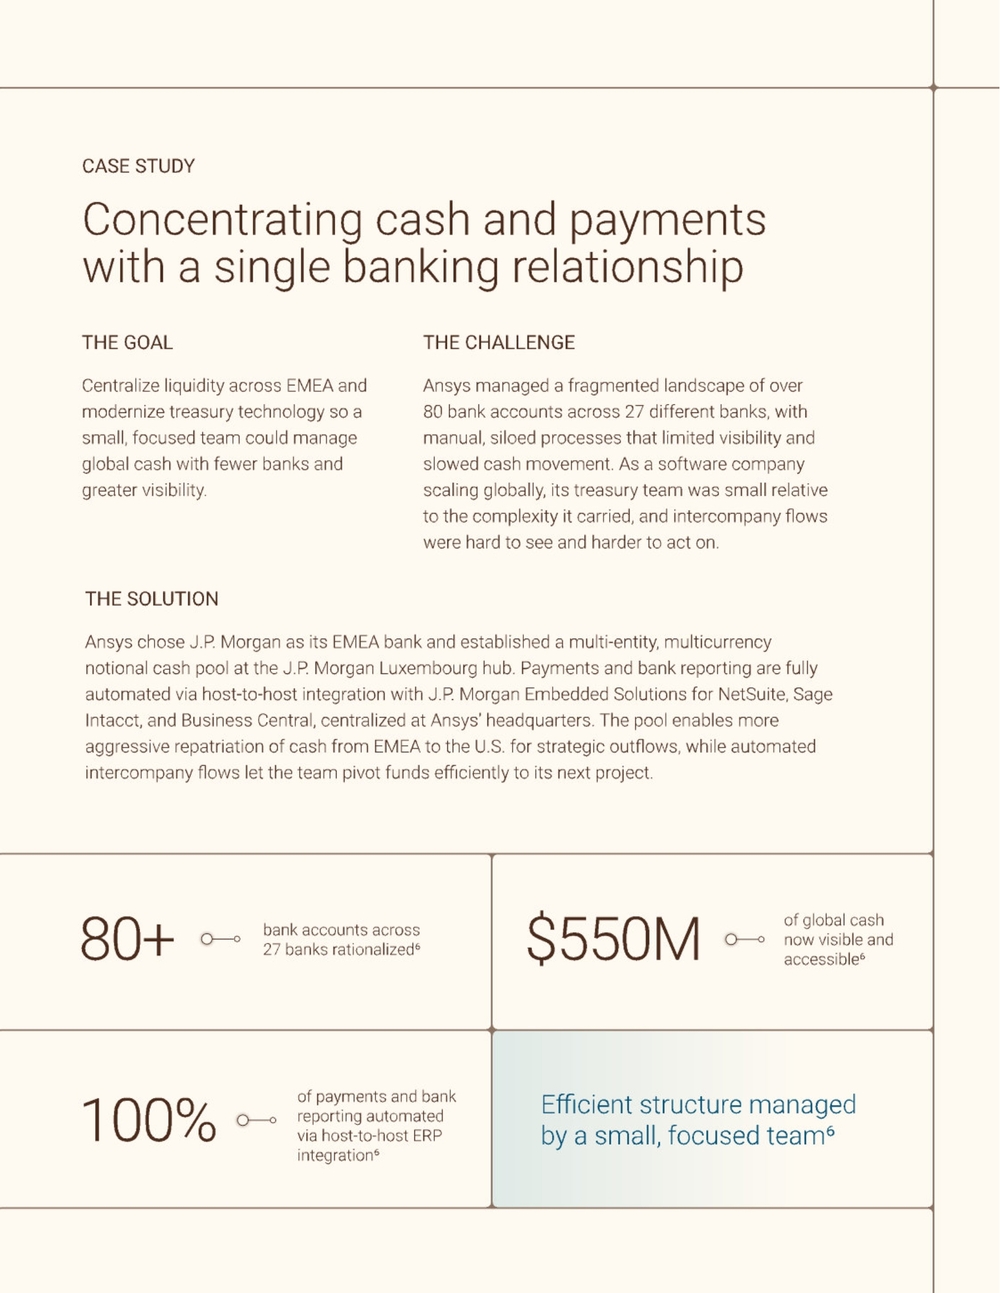
Case Stud yConcentr ating cash and pa yments with a single banking r elationshipTHE GO ALThe ch allengeCentr aliz e liquidity acr oss EMEA and moderniz e tr easur y technology so a small, focused team could manage global cash with f ewer banks and gr eater visibility .Ansys managed a fr agmented landscape of o v er 80 bank accounts acr oss 27 diff er ent banks, with manual, siloed pr ocesses that limited visibility and slowed cash mo v ement. As a softwar e company scaling globally , its tr easur y team was small r elativ e t o the complexity it carried, and inter company flows wer e har d t o see and har der t o act on.THE SOL UTIONAnsys chose J.P . Mor gan as its EMEA bank and established a multi-entity , multicurr ency notional cash pool at the J.P . Mor gan L ux embour g hub. P a yments and bank r epor ting ar e fully aut omated via host-t o-host integr ation with J.P . Mor gan Embedded Solutions for NetSuite, Sage Intacct, and Business Centr al, centr aliz ed at Ansys’ headquar ters. The pool enables mor e aggr essiv e r epatriation of cash fr om EMEA t o the U.S. for str ategic outflows, while aut omated inter company flows let the team piv ot funds efficiently t o its next pr oject.8 0 +bank accounts acr oss 27 banks r ationaliz ed⁶$ 5 5 0 Mof global cash now visible and accessible⁶1 0 0 %of pa yments and bank r epor ting aut omated via host-t o-host ERP integr ation⁶Efficient structur e managed b y a small, focused team⁶
Why work with usF r agmentation is not just inefficient; it’ s a gr owth tax. The companies that consolidate t o a single, capable banking r elationship fr ee up capital, r educe f ees, and giv e tr easur y the connected view that turns cash management fr om a cost center int o a str ategic asset.
Let’ s end the fr agmentation tax and giv e y our tr easur y the one connected view it needs. T alk t o y our J.P . Mor gan P a yments r epr esentativ e about a banking r elationship consolidation assessment t oda y . The Currency of ProgressP ower ed b y J.P . Mor gan P a yments1 Deloitte, “2024 Global Corpor ate T r easur y Sur v e y, ” 2024. 2 Tiet oe vr y Banking, “2024 Cash Management Sur v e y, ” 2024. 3 PYMN T S Intelligence & Citi, “The Impact of Misunderst ood T r easur ers in T echnology, ” 2024. 4 EY , “Cash for ecasting: Difficult and mor e ur gent than e v er, ” 2024. 5 PwC, “2025 Global T r easur y Sur v e y, ” 2025. 6 J.P . Mor gan, “Leading EMEA T r easur y T r ansformation for Ansys, ” 2024. 7 Str ategic T r easur er , “2025 T r easur y P erspectiv es Sur v e y , ” 2025. 8 Association of Corpor ate T r easur ers & K yriba, “T aking the Pulse” T r easur y Sur v e y , 2024D isclaimer i nformation