Banks_Infographics_Value&Trust
by JPMorgan
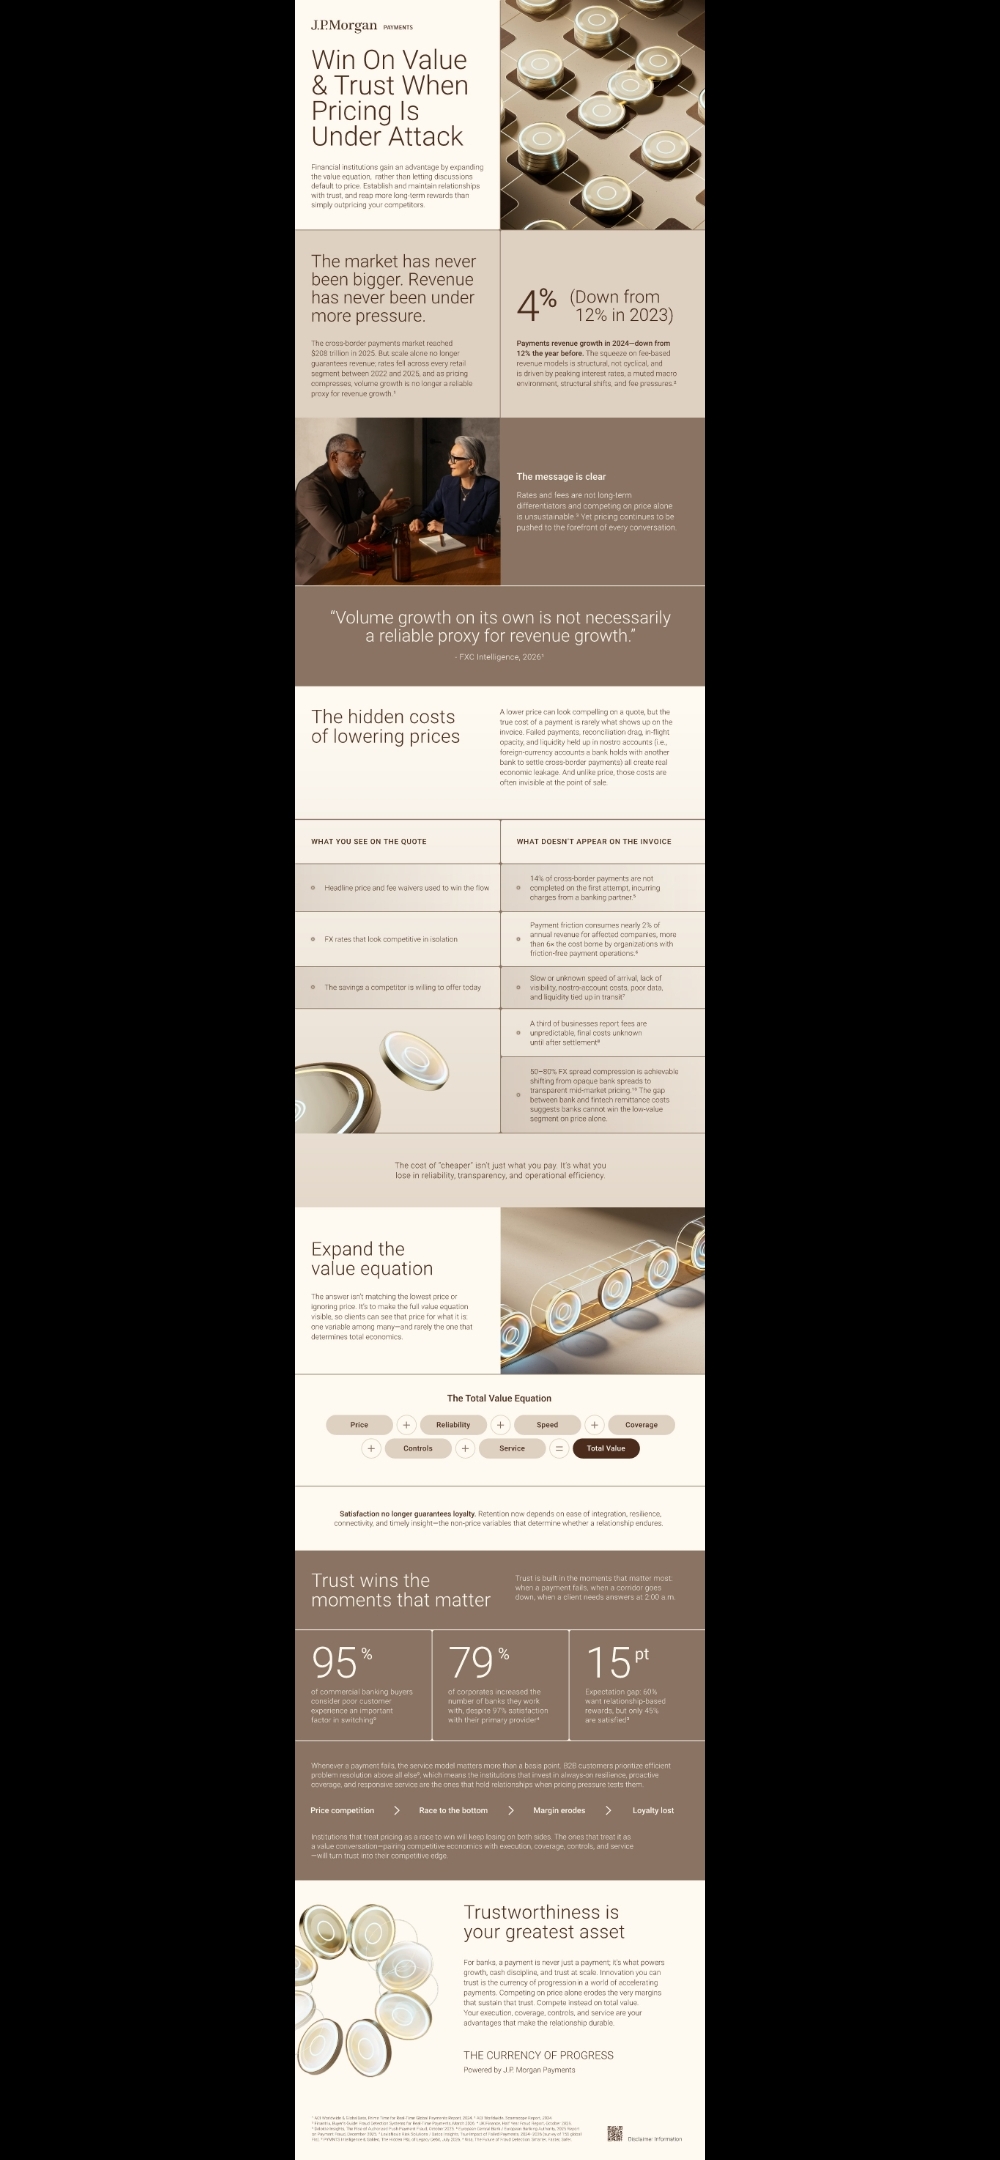
Win On V alue & T rust When Pricing Is Under A ttack Financial institutions gain an adv antage b y expanding the v alue equation, r ather than letting discussions default t o price. Establish and maintain r elationships with trust, and r eap mor e long-term r ewar ds than simply outpricing y our competit ors. The mark et has ne v er been bigger . Re v enue has ne v er been under mor e pr essur e.The cr oss-bor der pa yments mark et r eached $208 trillion in 2025. But scale alone no longer guar antees r e v enue; r ates f ell acr oss e v er y r etail segment between 2022 and 2025, and as pricing compr esses, v olume gr owth is no longer a r eliable pr o xy for r e v enue gr owth.¹(D own fr om 1 2 % in 202 3)4%P a yments r e v enue gr owth in 2024—down fr om 12% the y ear befor e. The squeez e on f ee-based r e v enue models is structur al, not cy clical, and is driv en b y peaking inter est r ates, a muted macr o envir onment, structur al shifts, and f ee pr essur es.² The message is clearRates and f ees ar e not long-term diff er entiat ors and competing on price alone is unsustainable. ³ Y et pricing continues t o be pushed t o the for efr ont of e v er y conv ersation. “V olume gr owth on its own is not necessarily a r eliable pr o xy for r e v enue gr owth. ”- F X C I n t e l l i g e n c e , 2 0 2 6 ¹ T h e h i d d e n c o s t s o f l o w e r i n g p r i c e s A lower price can look compelling on a quote, but the true cost of a pa yment is r ar ely what shows up on the inv oice. F ailed pa yments, r econciliation dr ag, in ‑ flight opacity , and liquidity held up in nostr o accounts ( i.e., for eign-curr ency accounts a bank holds with another bank t o settle cr oss-bor der pa yments ) all cr eate r eal economic leakage. And unlik e price, those costs ar e often invisible at the point of sale. W h at y o u s e e o n t h e q u o t e H eadline price and f ee waiv ers used t o win the flow FX r ates that look competitiv e in isolation The sa vings a competit or is willing t o off er t oda y W h at d o e s n ’ t a p p e a r o n t h e i n v o i c e 14% of cr oss-bor der pa yments ar e not completed on the first attempt, incurring char ges fr om a banking par tner .5P a yment friction consumes nearly 2 % of annual r e v enue for aff ected companies, mor e than 6 × the cost borne b y or gani z ations with friction-fr ee pa yment oper ations. ⁶ S low or unknown speed of arriv al, lack of visibility , nostr o-account costs, poor data, and liquidity tied up in tr ansit ⁷ A thir d of businesses r epor t f ees ar e unpr edictable, final costs unknown until after settlement ⁸ 50–80% FX spr ead compr ession is achie v able shifting fr om opaque bank spr eads t o tr anspar ent mid-mark et pricing.10 The gap between bank and fintech r emittance costs suggests banks cannot win the low-v alue segment on price alone.T h e c o s t o f “ c h e a p e r ” i s n ’ t j u s t w h a t y o u p a y . I t ’ s w h a t y o u l o s e i n r e l i a b i l i t y , t ra n s p a r e n c y , a n d o p e ra t i o n a l e f f i c i e n c y . E x p a n d t h e v a l u e e q u a t i o n The answer isn ’t matching the lowest price or ignoring price. It’ s t o mak e the full v alue equation visible, so clients can see that price for what it is: one v ariable among many—and r ar ely the one that determines t otal economics. P r i c eC o n t r o l sThe T ot al V al u e E qu a t i on R e l i a b i l i t yS p e e dS e r v i c eC o v e r a g eT o t a l V a l u eSatisfaction no longer guar antees lo y alty . Retention now depends on ease of integr ation, r esilience, connectivity , and timely insight—the non-price v ariables that determine whether a r elationship endur es. T r u s t w i n s t h e m o m e n t s t h a t m a t t e r T r u s t i s b u i l t i n t h e m o m e n t s t h a t m a t t e r m o s t : w h e n a p a y m e n t f a i l s , w h e n a c o r r i d o r g o e s d o w n , w h e n a c l i e n t n e e d s a n s w e r s a t 2 : 0 0 a . m . 9 5%o f c o m m e r c i a l b a n k i n g b u y e r s c o n s i d e r p o o r c u s t o m e r e x p e r i e n c e a n i m p o r t a n t f a c t o r i n s w i t c h i n g ⁹ 7 9%o f c o r p o ra t e s i n c r e a s e d t h e n u m b e r o f b a n k s t h e y w o r k w i t h , d e s p i t e 9 7 % s a t i s f a c t i o n w i t h t h e i r p r i m a r y p r o v i d e r ⁴ 1 5ptE x p e c t a t i o n g a p : 6 0 % w a n t r e l a t i o n s h i p - b a s e d r e w a r d s , b u t o n l y 4 5 % a r e s a t i s f i e d ³ Whene v er a pa yment fails, the ser vice model matters mor e than a basis point. B2B cust omers prioriti z e efficient pr oblem r esolution abo v e all else ⁹ , which means the institutions that inv est in alwa ys-on r esilience, pr oactiv e co v er age, and r esponsiv e ser vice ar e the ones that hold r elationships when pricing pr essur e tests them. P rice c o m p e t i t i onR ace t o t he bott o mM ar gi n er od es L o y al ty l o s tInstitutions that tr eat pricing as a r ace t o win will k eep losing on both sides. The ones that tr eat it as a v alue conv ersation—pairing competitiv e economics with ex ecution, co v er age, contr ols, and ser vice —will turn trust int o their competitiv e edge. T r u s t w o r t h i n e s s i s y o u r g r e a t e s t a s s e tF or banks, a pa yment is ne v er j ust a pa yment; it’ s what powers gr owth, cash discipline, and trust at scale. Inno v ation y ou can trust is the curr ency of pr ogr ession in a world of acceler ating pa yments. Competing on price alone er odes the v er y mar gins that sustain that trust. Compete instead on t otal v alue. Y our ex ecution, co v er age, contr ols, and ser vice ar e y our adv antages that mak e the r elationship dur able. T he C urrency of P rogressP ower ed b y J .P . M or gan P a yments 1 A C I W o r l d w i d e & G l o b a l D a t a , P r i m e T i m e f o r R e a l - T i m e G l o b a l P a y m e n t s R e p o r t , 2 0 2 4 . 2 A C I W o r l d w i d e , S c a m s c o p e R e p o r t , 2 0 2 4 . 3 F i n a n t r i x , B u y e r ’ s G u i d e : F ra u d D e t e c t i o n S y s t e m s f o r R e a l - T i m e P a y m e n t s , M a r c h 2 0 2 6 . 4 U K F i n a n c e , H a l f Y e a r F ra u d R e p o r t , O c t o b e r 2 0 2 5 . 5 D e l o i t t e I n s i g h t s , T h e R i s e o f A u t h o r i z e d P u s h P a y m e n t F ra u d , O c t o b e r 2 0 2 5 . 6 E u r o p e a n C e n t ra l B a n k / E u r o p e a n B a n k i n g A u t h o r i t y , 2 0 2 5 R e p o r t o n P a y m e n t F ra u d , D e c e m b e r 2 0 2 5 . 7 L e x i s N e x i s R i s k S o l u t i o n s / D a t o s I n s i g h t s , T r u e I m p a c t o f F a i l e d P a y m e n t s , 2 0 2 4 – 2 0 2 6 ( s u r v e y o f 1 5 0 g l o b a l F I s ) . 8 P Y M N T S I n t e l l i g e n c e & G a l i l e o , T h e H i d d e n P & L o f L e g a c y D e b i t , J u l y 2 0 2 6 . 9 V i s a , T h e F u t u r e o f F ra u d D e t e c t i o n : S m a r t e r , F a s t e r , S a f e r . D isclaimer i nformation